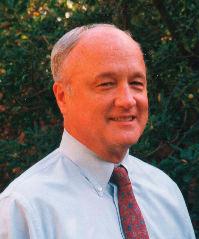
Paul Beretz, CICE (Certified International Credit Executive), is Managing Director of Pacific Business Solutions, a company he created in 1999. In addition, he is a founding partner of Q2C (Quote to Cash) Solutions. He brings over 30 years of global, corporate experience in finance and management with industries such as telecommunications, semi-conductors, forest products, chemicals, plastics and consumer products among others. His expertise includes analyzing opportunities and providing resolutions in the order-through-collect cycle for manufacturers, distributors and service companies located worldwide.
Paul is a faculty member at St. Mary’s College (CA), instructing working professionals who
are in the process of completing either their BA or MA in the program of Leadership and Organizational Studies. In addition, he directs students completing their final project in the MA in Social Justice course. Paul has taught adult learners at UC Berkeley, Michigan State University, Arizona State University and an executive summer course at Dartmouth College.
He was responsible for developing and teaching a a successful international on line course for the FCIB association, (Finance Credit and International Business) In 2011, ICTF (International Credit and Trade Finance) association requested Paul instruct on line courses through an affiliation with Thunderbird School of Global Management, a very highly rated management institution. Also, at the request of the California Business Credit Association (CMA), he created and instructs in two online certificate courses, “Financial Statement Analysis” and “Business Credit Principles.”
Mr. Beretz has given over 350 presentations and in-house training programs to Fortune 500 companies, associations and professional groups. He has been an expert witness, written articles for trade publications such as Business Credit and IOFM (Institute of Finance & Management), quoted by news organizations (e.g., Bloomberg), is a member of the Advisory Editorial Board of IOFM's publication, Managing Credit, Receivables & Collections, edits books on financial management and authored a book for the American Management Association on credit management. In 2009, he was asked to contribute an article on "Essentials for Export Success" for QFinance, a 2,000-page book, published by Bloomsbury Press, UK.
In 2007, Paul was awarded a Certificate of Appreciation by the Under Secretary for International Trade of the U.S. Department of Commerce for his contributions to the “Trade Finance Guide,” a reference publication produced by the Commerce Department for U.S. exporters. More than 100,000 copies have been distributed (in print and via online)to the public. Mr. Beretz served as a member of the Advisory Committee of the Export-Import Bank of the U.S. for 2008-2009. Paul also received the "Credit Executive Award of 2008" from CMA (the California Business Credit Association) and in 2013 was named "Instructor of the Year"by CMA.
Paul earned his BBA from the University of Notre Dame, an MBA from Golden Gate University and the Executive Award at the Graduate School of Credit and Financial Management held at Stanford University.
Thursday, February 1, 2007


Thursday, November 16, 2006
FCIB Panel: Dimensions of Country Risk
At the annual global conference of the Association of Executives in Finance, Credit and International Business (FCIB) held in Coral Gables, Florida, November 12-14, a well-attended panel on "Fundamentals of Export Credit Management" provided a wealth of practical, hands-on advice for assessing global credit risks. The full schedule is here.
As a featured panelist I can provide you with more information. Contact me if interested.
As a featured panelist I can provide you with more information. Contact me if interested.
Saturday, September 30, 2006
Negotiation skills for credit managers
Here are some slides from the NACM Western Region Credit Conference. The session was entitled, "Negotiation Skills: a Workshop for Credit Managers."
Thursday, December 22, 2005
The International Obstacle Course
The International Obstacle Course
By William Atkinson
Clearing the hurdles of credit and collections overseas requires training, excellent teamwork, and frequently a third-party’s helping hand.
International business represents a substantial portion of total business for a lot of companies. That can be a benefit or a drawback. On the one hand, business from varied markets can be good for a company’s growth. On the other hand, it can create an exposure to more risk than domestic credit and collections.
One significant challenge is managing country risk – changes in a nation’s economy or government, currency issues, and so on. “It is difficult to stay on top of all this,” explains Paul Beretz, founder and managing director of Pacific Business Solutions and a partner with Q2C, Clayton, Calif. “For example, you may have a customer who pays like clockwork every 30 days, but if something changes in his country, that can jeopardize those payments.”
Knowing the ins and outs of international credit and collections can significantly reduce risks. A couple of years ago, for example, Corning Cable Systems in
“Even though we were granting extended terms because of the construction times on the projects, the availability of simple documentation and the discounting of the letters of credit allowed us to receive our funds well in advance of the due dates,” explains Thomas Brady, credit manager. The key was utilizing a network of banks throughout the
Another challenge with international credit and collections is that very little “generic” knowledge applies to all countries. Each area of the world is unique in many ways, so once the few “basics” have been mastered, gaining expertise in each country, region, or continent is the next step. Following are challenges for international trade in some key areas of the world.
According to Jason Probst, director, international business development for D&B Receivable Management Services,
Banks are trying to establish histories to bring some order to the situation. Meanwhile, over the past three years the government has been selling millions of dollars of non-performing loans, or NPLs. Foreign investment firms, including many from the U.S., have been purchasing the portfolios at a discount. “One of these firms uses us to do their NPL collections,” Probst notes.
Brady has found it difficult to get financial statements and other standard information from customers in
Even if a firm feels comfortable with these companies and begins doing business with them, they can still run into payment problems. Brady cites a couple of examples: If a firm offers 30-day terms and provides next-day air shipment, the customer may pay in 60 to 90 days. If the firm offers 60-day terms and provides ocean carrier shipments, that customer may pay in 90 days. One reason, he says, is that the Chinese bureaucracy tends to add 30 or more days to the process for importation of goods, customs clearance, foreign exchange approvals, and so on.
To address these concerns,
According to D&B’s Probst, many
In the late 1990s, European countries began to realize that late payments were a serious problem for the economy – costing numerous jobs and millions of dollars in interest and export loss. The European Commission attempted to implement late payment legislation to set out a clear path for companies to get paid on time. “It’s now four years later, and the legislation hasn’t done much,” says Probst. The reason: It hasn’t been accepted at the commercial level in the countries.
“In fact,” he adds, “payment delays continue to get worse.” In addition, the legal enforcement infrastructure designed to help companies collect actually impedes the collections process in most countries. (The Nordic countries are an exception.) “The European Commission,” he reports “is reviewing the legislation this year with an eye toward streamlining it to make it easier for companies to get paid.”
Until recently, electronic invoicing (wire transfers) was not legal in
While other countries can be a problem, doing business with Canadian customers should be a cakewalk, right? Not really. “Most people don’t realize it, but there are some distinct differences between doing business in
And trying to collect from companies in the far-flung areas of
International Strategies
To navigate through the confusing maze of international credit and collections issues, experts recommend three general strategies: education, internal teamwork and vigilance, and third-party assistance.
Education: “While there are some good education programs on international credit and collections, such as seminars about what’s going on in different parts of the world, widespread education is still lacking,” admits Pacific Business Solution’s Beretz. “In addition, it is difficult for credit people to get together and talk about international trends.”
One program Beretz recommends, both for the education offered and the opportunity to network, is a three-month online certificate offered by FCIB and
D&B Receivable Management Services’ website (www.dbrms.com) offers a lot of information about the international credit and collections scene. In addition, D&B offers a free half-day international collections seminar. For information, contact Jason Probst at: probstj@dnb.com.
Internal Teamwork and Vigilance: “You need to be 100% accurate when dealing with other countries,” emphasizes
He also recommends staying on top of information, especially country risk. One way to do this is to have a good sales force in place in each country where you do business. “They can help you get ahead of any problems before they develop,” he explains.
Pay attention to documentation. “One major difference between international and domestic credit is that the former requires significantly more amounts of documentation,” explains D&B’s Probst. “There are a variety of terms of sale, only one of which is the letter of credit.” In addition, there are more opportunities these days to transmit documents electronically, which can reduce inaccuracies and time delays.
Third-Party Assistance: It’s no shame to lack comprehensive international expertise on staff. In fact, most companies find it to their advantage to utilize a variety of third-party providers who specialize in various aspects of international credit and collections.
“Letters of credit have so many intricacies that it is easy to end up with discrepancies,” notes Beretz. “Few companies want to hire a specialist on staff to handle this responsibility. One alternative is to use third-party providers that specialize in handling letters of credit.”
Some large banks are also excellent sources of assistance. “A lot more banks these days, especially the big ‘money center’ banks, are getting into the business of managing international credit and collections activities for companies as part of their receivables management services,” states Jerry Topitzer, vice president-head of structured trade finance, for JPMorgan, New York. Such services include the creation of export documents as well as taking the receivables created from those documents and providing discounted financing.
Another relatively new service area in the international arena is the credit derivative, often called a credit default swap or CDS. “These can be used in hedging situations for large concentrations of risk in receivables portfolios,” explains Topitzer. For example, if a firm is doing business with a government in an emerging market and can get a ministry of finance guarantee on obligations arising out of the contracts, it can consider buying CDS contracts on that particular sovereign borrower. “In so doing, though,” Topitzer warns, “you need to make sure that you completely understand what the CDS contracts really cover.”
In sum, international credit and collections is a quagmire of confusion and challenges for most credit professionals. Still, because of the potential for increased business that international sales represent, credit professionals cannot afford to ignore it.
Still there’s no need to go it alone. Look for educational opportunities to learn as much as possible. Then, don’t be afraid to rely on third-party specialists to help hurdle the obstacles.
_____
Helping Hands
Every now and then we all need a little help from our friends. Here are some resources to help get over those international hurdles.
FCIB (Finance, Credit and International Business)
An association of executives in finance, credit, and international business. For information on FCIB and its on-line international credit management program with
D&B Receivable Management Services
For information on D&B’s international credit and collections seminars, contact:
Jason Probst, Director, International Business Development, via phone: 484-242-7494 or e-mail: probstj@dnb.com
Coface
An international credit services company that provides credit insurance, debt recovery, credit risk information, receivables management, factoring, and receivables securitization. For information on Coface’s Country Risk Conference and its Country Risk Guide, containing macroeconomic and sector information on more than 140 countries, visit the Events section on www.coface.com. For information on Coface’s Country Ratings, visit www.cofacerating.com.
International Association of Commercial Collectors
For help in locating members that are based in and/or provide collections services in foreign countries, check out IACC’s online directory, which you can search by country, at www.commercialcollector.com.
© Copyright 2005 The Thomson Corp. and Collections & Credit Risk. All rights reserved.
Friday, September 22, 2000
Stop, Look and Listen! : Expert Advice on Doing Business in the Pac Rim
Stop, Look and Listen! : Expert Advice on Doing Business in the Pac Rim
By Paul Beretz
(Reprinted with permission from IOMA's Report on Managing International Credit and Collections, September 2000 issue).
Understanding cultural nuances can be the difference between success and failure when dealing with customers in other countries. Most international credit executives are well aware of this fact and strive to avoid the obvious land mines. Yet, even the most seasoned international credit professional occasionally stumbles, especially when transacting business in the Pacific Rim, where business attitudes and behaviors are quite different than what most U.S. managers are accustomed to. MICC recently spoke with veteran credit professional and experienced traveler, Paul Beretz, about how international credit professionals could avoid cultural blunders when traveling to the Pacific Rim.
Observation
"In the Pacific Rim business environment," says Beretz, a managing director of Pacific Business Solutions, "the observant credit manager will remember the sign they may have seen at railroad crossings: "Stop, Look, and Listen!" He warns that this includes not only dealing with customers offshore, but also with a company's own "internal" customer, the branch office in the overseas country.
The international credit professional must be aware of many subtleties. To be successful in the Pacific Rim countries, the international credit professional will study behavior, learn about verbal and nonverbal differences that exist, and probably use a "go-between" (a shokaijo in Japan) to help develop the desired relationship. "The credit manager should understand how important the go-between is in the Pac Rim country," warns Beretz. That person may be the seller's country manager, a banker, accountant, or individual in a key position in the country who understands how to help achieve the objective.
Will credit managers understand that an immediate decision-in the expected, American way-may not be forthcoming in a Pacific Rim culture? Open conflict and public emotional displays are also counter to the culture that they are dealing with.
Trust
In the United States, trust is rarely an issue when conducting business. In the Pacific Rim, trust is extremely important and those who ignore it do so at the peril of their business. Trust takes time to build, adding to the frustration many feel when doing business in the Pacific Rim. (The same frustrations apply to Latin America.)
"In the Pac Rim," says Beretz, "cultures depend on trust, or the 'oil of life' as defined in Japan, known as amae." He warns that in any relationship in this region, a feeling of complete trust and confidence must exist, not only so that the other party will not take advantage of him but also so that he count on the indulgence of the other. Most American international credit executives are accustomed to some-thing quite different from this.
Those deemed most qualified for leadership positions in this region are perceived as being dependent on those people beneath them. "This is the purest form of an egoless relationship, which contrasts with the need to repress trust that Western societies foster," he says.
Listening is not easy for many Americans. Interrupting is second nature for some. Beretz says it is undoubtedly the origin for the Japanese saying "hollow drums make the most noise." One of the hardest concepts for Americans to understand is that many in the Pacific Rim will consider a matter for a while before answering. Long pauses tend to make Americans feel that they have to jump in and fill the void. Don't. Let your customer take time to think before answering. Having the international credit executive also think before answering is not a bad idea, especially since the silence will not put off your Pacific Rim host.
Examples of How Observation Can Work
How to Negotiate When Using an Interpreter
While English has truly become the international language, in the Pacific Rim, top executives have not mastered (or didn't care to master) it. In these cases, using an interpreter can help. However, the following caveats should be considered:
By Paul Beretz
(Reprinted with permission from IOMA's Report on Managing International Credit and Collections, September 2000 issue).
Understanding cultural nuances can be the difference between success and failure when dealing with customers in other countries. Most international credit executives are well aware of this fact and strive to avoid the obvious land mines. Yet, even the most seasoned international credit professional occasionally stumbles, especially when transacting business in the Pacific Rim, where business attitudes and behaviors are quite different than what most U.S. managers are accustomed to. MICC recently spoke with veteran credit professional and experienced traveler, Paul Beretz, about how international credit professionals could avoid cultural blunders when traveling to the Pacific Rim.
Observation
"In the Pacific Rim business environment," says Beretz, a managing director of Pacific Business Solutions, "the observant credit manager will remember the sign they may have seen at railroad crossings: "Stop, Look, and Listen!" He warns that this includes not only dealing with customers offshore, but also with a company's own "internal" customer, the branch office in the overseas country.
The international credit professional must be aware of many subtleties. To be successful in the Pacific Rim countries, the international credit professional will study behavior, learn about verbal and nonverbal differences that exist, and probably use a "go-between" (a shokaijo in Japan) to help develop the desired relationship. "The credit manager should understand how important the go-between is in the Pac Rim country," warns Beretz. That person may be the seller's country manager, a banker, accountant, or individual in a key position in the country who understands how to help achieve the objective.
Will credit managers understand that an immediate decision-in the expected, American way-may not be forthcoming in a Pacific Rim culture? Open conflict and public emotional displays are also counter to the culture that they are dealing with.
Trust
In the United States, trust is rarely an issue when conducting business. In the Pacific Rim, trust is extremely important and those who ignore it do so at the peril of their business. Trust takes time to build, adding to the frustration many feel when doing business in the Pacific Rim. (The same frustrations apply to Latin America.)
"In the Pac Rim," says Beretz, "cultures depend on trust, or the 'oil of life' as defined in Japan, known as amae." He warns that in any relationship in this region, a feeling of complete trust and confidence must exist, not only so that the other party will not take advantage of him but also so that he count on the indulgence of the other. Most American international credit executives are accustomed to some-thing quite different from this.
Those deemed most qualified for leadership positions in this region are perceived as being dependent on those people beneath them. "This is the purest form of an egoless relationship, which contrasts with the need to repress trust that Western societies foster," he says.
Listening is not easy for many Americans. Interrupting is second nature for some. Beretz says it is undoubtedly the origin for the Japanese saying "hollow drums make the most noise." One of the hardest concepts for Americans to understand is that many in the Pacific Rim will consider a matter for a while before answering. Long pauses tend to make Americans feel that they have to jump in and fill the void. Don't. Let your customer take time to think before answering. Having the international credit executive also think before answering is not a bad idea, especially since the silence will not put off your Pacific Rim host.
Examples of How Observation Can Work
- Japan. In Japan, the concept of wa, meaning peace and harmony, is the basis for a working relationship. The highest priority is placed on wa. The Japanese person with closed eyes sitting opposite the credit manager is not necessarily being rude-he may be working towards inner harmony. "Speech is silver, silence is golden."
- Korea. In Korea, the priorities are family, respect for authority, formality, and class. Koreans are aggressive, hardworking, friendly, and hospitable. A driving force in Korean relationships (and significant in all Pacific Rim countries to a degree) is "saving face." If no one points out any errors to the people responsible, the person might assume that no errors exist, so no "face" is lost.
How to Negotiate When Using an Interpreter
While English has truly become the international language, in the Pacific Rim, top executives have not mastered (or didn't care to master) it. In these cases, using an interpreter can help. However, the following caveats should be considered:
- The presenter (the credit manager visiting his customer, for example, needs to find his or her own interpreter, probably through a go-between in the country.
- A written text of the presentation (or at least, the gist of the notes for the meeting) needs to be given to the interpreter.
- The English speaker should speak slowly around a single topic, avoid slang and puns, and only use metaphors and analogies with care. For example, would the speaker expect an interpreter to translate "what's good for the goose, is good for the gander" into an Asian language?
- Charts and visuals should be used whenever possible.
- Monitor facial and nonverbal expressions, and talk to the person, not the interpreter.
- A little humility. Those who travel from the United States to Asian nations in particular need to stop promoting the United States. ("That may be the way you write a contract here in China, but that's not the way we do it in the United States" or "Can't I find American food anywhere around this place?") These Americans are visiting their host, not the other way around.
- Idioms. Why are we not more conscious of the use of idioms? Idiomatic phrases are extremely difficult for non-U.S. people to understand. Just think how a customer sitting across the table in countries such as China, Japan, South Korea, Vietnam, or Taiwan may react when phrases such as "better late than never," "in the long run," "put it on the back burner," "get the ball rolling," "get to first base," "quick on the trigger," and "beat around the bush" are used.
- Business cards etiquette. Does the westerner stop to appreciate the significance of the "name" (business) card in Pac Rim countries? The high number of visitors to Asian nations who do not have the native language printed on business cards (especially if one does extensive, repeat business in Japan or China, for example) is amazing. The card is presented with both hands, with a slight bow or ojigi ("oh-jee-ghee" in Japanese). The name of the other person's company is looked at closely, and the cards are not written on or put away during the meeting. An insult tendered at the beginning of the meeting-even an unintentional slight-can destroy the chance for any successful outcome.
- Group consensus. Japan's cultural roots have a strong middle management that has deep working relationships and seniority in rank. Japanese managers look after subordinates. Management is participative, problems are solved by consensus, and there is no open expression of conflict. A humble attitude by public figures especially is still considered an essential virtue. Westerners should realize that apologies in this culture may be real as well as "pretended" in the same way that Americans brag about their imagined skills. The purpose of the Japanese apology is to avoid ill will, friction, and anything else that may be seen as wrong.
International Skills: Don't Leave Home Without Them
International Skills: Don't Leave Home Without Them
By Sherry Schlossnagle
(Reprinted from the September 2000 issue of Business Credit magazine with permission of NACM.).
I asked Beretz to comment on the current changes occurring in the international credit industry.
"The key word here is consolidation -- both international and in North America," he replied thoughtfully. "More and more credit jobs are being consolidated. As a result, the role of the international credit manager is not only becoming more decentralized with those managers outside the country reporting back to the chief credit manager, but it is also evolving more into the role of a risk manager that may include insurance and cash management along with the credit function."
Beretz believes that it is imperative for all credit managers to begin to develop international skills. In light of this necessity, he emphasized the value of participating in FCIB. "FCIB can play a very important and pivotal role in the development of the international credit professional's career. It not only attunes the credit manager to an awareness of international business; it also provides tools, and educational and networking opportunities."
As a member of the Advisory Council, Beretz discussed some of the challenges that FCIB faces at this time. "Our primary focus should be how we recruit and retain our membership. FCIB is in the process of investigating a variety of new products that will address the needs of global clients. It is also discussing the development of new educational projects, as well as how to revitalize the existing ones. The issue of `time commitment' of members is another very important consideration -- more important even than cost, I think. We must be very accurate in targeting those products and services to meet membership needs since professionals are becoming more selective in attending meetings and participating in programs.
The second challenge we face has to do with the issue of `global awareness.' As businesses continue to expand globally, it is critical to their success that they understand what their international customers need and how to conduct business in the customer's own environment. FCIB can play a role in assisting members who want to achieve an expanded level of awareness.
The third challenge is the continued development of the Internet application to link members to more new products and services, as well as to facilitate and enhance the online communication process. It is important that FCIB continues to update its Internet applications and solutions and expands its web site to meet membership needs."
Regarding the value of the FCIB Certified International Credit Executive (CICE) designation, Beretz believes the new professional designation has provided an excellent vehicle to recognize and reemphasize that international credit management is a very specialized area of knowledge critical to business. "The CICE not only adds to the professional's credibility within the company and the industry, it is respected in other cultures as well."
Beretz began participating in FCIB in 1983 while he was working for the forest products industry. He has continued his FCIB membership in the semi-conductor and telecommunications industries in the `90s. "I knew next to nothing about international credit management when I first started out, so I went to FCIB for help. Of the many benefits available through FCIB, the two I value most are the networking and the educational opportunities. The professional network that I have developed through my participation in FCIB over the past 17 years is invaluable. I can call any number of people at any time and say that I have a client doing business in, let's say, Ethiopia and ask them about the credit situation there. These resources have the most current and accurate information available." Beretz was also quick to note that he utilizes the FCIB Country and Customer reports that are unique to the industry and provide very specialized information.
"I try to attend as many FCIB-sponsored regional and global meetings as I can. There is a tremendous amount of knowledge and wisdom shared at these meetings. Being privy to this very specialized information makes me more globally aware than I could possibly be otherwise. If international credit managers intend to operate successfully within a country, it is imperative that they be aware of and sensitive to the differences in cultures and customs."
As Managing Director of Pacific Business Solutions -- a consulting firm that evaluates and creates opportunities to improve cash flow for global manufacturing, distribution and service companies -- Beretz has successfully capitalized on more than 30 years of business experience.
For start-up to middle market sized companies, he has initiated tactical and strategic processes, guided management to evaluate the market place and competition, established personnel performance measures and utilized budgeting and forecasting tools. For middle market and larger companies, he has formulated "best practice" strategies, reorganized departments, and re-defined and authored "desk procedures" for worldwide operations. On the international level he has provided guidance to several multi-billion dollar companies in the recognition of economic, country, and cultural issues fundamental to selling products and services internationally, particularly in Pacific Rim countries.
Beretz received his BBA from the University of Notre Dame and an MBA from Golden Gate University. He has been an adjunct faculty member at the University of California, Berkeley and currently is an instructor in management and finance for St. Mary's College, Moraga, CA and the University of Phoenix. In addition, he speaks frequently covering a wide range of topics from cash flow management techniques to customs and practices in international business. He has written articles for trade magazines such as IOMA's Report on Managing International Credit and Collections and NACM's Business Credit, authored a book for the American Management Association and edited books on financial management.
I remarked that a business background such as his own was probably one of the major criteria for hiring someone to work in the credit profession. "On the contrary," Beretz replied, "I place great value on a strong liberal arts education. It is becoming increasingly more important for credit professionals to have well-developed verbal and writing skills, as well as an acquaintance, if not a familiarity, with other philosophies and cultures. A good liberal arts education should provide all of these. I can educate bright employees on the technical side of the business, but I can't teach them to be articulate or good writers or make them critical thinkers. If I can have both, then I have the best of both worlds."
Regarding his greatest professional challenges, "Two immediately come to mind," he replied. "First is the constant `selling' of credit within the organization to make certain that it is understood. The astute credit manager will always keep going back to ensure that upper management understands what the credit manager is doing with the receivables. You can't take that understanding for granted. It is an ongoing challenge to keep the appropriate people educated.
The second challenge deals with the issue of isolation. Credit people are often very alone because the company in general doesn't really understand what they do. There is this `shroud of mystery' surrounding the credit operation. To address this isolation problem, management should support credit managers in their desire to join professional associations where they can network, share problems and discuss common issues. FCIB, of course, is the perfect example of an association that offers such networking and education opportunities for credit professionals."
Over the years Beretz has been a speaker at numerous FCIB and NACM conferences and meetings. He will be leading a panel on International Credit Scoring at the FCIB Global Meeting in New York City in November 2000.
Sherry Schlossnagle is a freelance writer based in Laurel, MD.
By Sherry Schlossnagle
(Reprinted from the September 2000 issue of Business Credit magazine with permission of NACM.).
I asked Beretz to comment on the current changes occurring in the international credit industry.
"The key word here is consolidation -- both international and in North America," he replied thoughtfully. "More and more credit jobs are being consolidated. As a result, the role of the international credit manager is not only becoming more decentralized with those managers outside the country reporting back to the chief credit manager, but it is also evolving more into the role of a risk manager that may include insurance and cash management along with the credit function."
Beretz believes that it is imperative for all credit managers to begin to develop international skills. In light of this necessity, he emphasized the value of participating in FCIB. "FCIB can play a very important and pivotal role in the development of the international credit professional's career. It not only attunes the credit manager to an awareness of international business; it also provides tools, and educational and networking opportunities."
| If you have not had the opportunity to read Beretz's publication, "How to Prepare for a Systems Application Installation or Upgrade," or his "Country Profiles" on how to handle credit and collections issues in South Korea and Singapore, then put them at the top of your To Do list. Not only do these articles offer a wealth of valuable information to professionals in the credit management field, they are also thought provoking and extremely well written. You can find them, as I did, on his website www.pacbizsolutions.com. |
The second challenge we face has to do with the issue of `global awareness.' As businesses continue to expand globally, it is critical to their success that they understand what their international customers need and how to conduct business in the customer's own environment. FCIB can play a role in assisting members who want to achieve an expanded level of awareness.
The third challenge is the continued development of the Internet application to link members to more new products and services, as well as to facilitate and enhance the online communication process. It is important that FCIB continues to update its Internet applications and solutions and expands its web site to meet membership needs."
Regarding the value of the FCIB Certified International Credit Executive (CICE) designation, Beretz believes the new professional designation has provided an excellent vehicle to recognize and reemphasize that international credit management is a very specialized area of knowledge critical to business. "The CICE not only adds to the professional's credibility within the company and the industry, it is respected in other cultures as well."
Beretz began participating in FCIB in 1983 while he was working for the forest products industry. He has continued his FCIB membership in the semi-conductor and telecommunications industries in the `90s. "I knew next to nothing about international credit management when I first started out, so I went to FCIB for help. Of the many benefits available through FCIB, the two I value most are the networking and the educational opportunities. The professional network that I have developed through my participation in FCIB over the past 17 years is invaluable. I can call any number of people at any time and say that I have a client doing business in, let's say, Ethiopia and ask them about the credit situation there. These resources have the most current and accurate information available." Beretz was also quick to note that he utilizes the FCIB Country and Customer reports that are unique to the industry and provide very specialized information.
"I try to attend as many FCIB-sponsored regional and global meetings as I can. There is a tremendous amount of knowledge and wisdom shared at these meetings. Being privy to this very specialized information makes me more globally aware than I could possibly be otherwise. If international credit managers intend to operate successfully within a country, it is imperative that they be aware of and sensitive to the differences in cultures and customs."
As Managing Director of Pacific Business Solutions -- a consulting firm that evaluates and creates opportunities to improve cash flow for global manufacturing, distribution and service companies -- Beretz has successfully capitalized on more than 30 years of business experience.
For start-up to middle market sized companies, he has initiated tactical and strategic processes, guided management to evaluate the market place and competition, established personnel performance measures and utilized budgeting and forecasting tools. For middle market and larger companies, he has formulated "best practice" strategies, reorganized departments, and re-defined and authored "desk procedures" for worldwide operations. On the international level he has provided guidance to several multi-billion dollar companies in the recognition of economic, country, and cultural issues fundamental to selling products and services internationally, particularly in Pacific Rim countries.
Beretz received his BBA from the University of Notre Dame and an MBA from Golden Gate University. He has been an adjunct faculty member at the University of California, Berkeley and currently is an instructor in management and finance for St. Mary's College, Moraga, CA and the University of Phoenix. In addition, he speaks frequently covering a wide range of topics from cash flow management techniques to customs and practices in international business. He has written articles for trade magazines such as IOMA's Report on Managing International Credit and Collections and NACM's Business Credit, authored a book for the American Management Association and edited books on financial management.
I remarked that a business background such as his own was probably one of the major criteria for hiring someone to work in the credit profession. "On the contrary," Beretz replied, "I place great value on a strong liberal arts education. It is becoming increasingly more important for credit professionals to have well-developed verbal and writing skills, as well as an acquaintance, if not a familiarity, with other philosophies and cultures. A good liberal arts education should provide all of these. I can educate bright employees on the technical side of the business, but I can't teach them to be articulate or good writers or make them critical thinkers. If I can have both, then I have the best of both worlds."
Regarding his greatest professional challenges, "Two immediately come to mind," he replied. "First is the constant `selling' of credit within the organization to make certain that it is understood. The astute credit manager will always keep going back to ensure that upper management understands what the credit manager is doing with the receivables. You can't take that understanding for granted. It is an ongoing challenge to keep the appropriate people educated.
The second challenge deals with the issue of isolation. Credit people are often very alone because the company in general doesn't really understand what they do. There is this `shroud of mystery' surrounding the credit operation. To address this isolation problem, management should support credit managers in their desire to join professional associations where they can network, share problems and discuss common issues. FCIB, of course, is the perfect example of an association that offers such networking and education opportunities for credit professionals."
Over the years Beretz has been a speaker at numerous FCIB and NACM conferences and meetings. He will be leading a panel on International Credit Scoring at the FCIB Global Meeting in New York City in November 2000.
Sherry Schlossnagle is a freelance writer based in Laurel, MD.
Subscribe to:
Posts (Atom)